Answer: Yes—many health insurance plans cover therapy, but coverage depends on your plan type (HMO, PPO, EPO, Medicaid, Medicare), network status, medical-necessity rules, copay/deductible structure, and whether teletherapy is permitted; always verify benefits and authorization requirements before scheduling to estimate out-of-pocket cost.
This guide explains how insurance covers therapy, shows step-by-step verification, defines key insurance terms, compares plan types, and offers cost examples and alternatives so you can determine whether your therapist is covered and what you’ll pay.
Overview of Insurance Coverage for Therapy
Answer: Insurance coverage for therapy varies — many plans include mental health benefits but differ on provider networks, session limits, copays, deductibles, and required authorizations.
Term: Insurance coverage for therapy means a health plan pays part or all of the cost of behavioral health services (counseling, psychotherapy, group therapy) when services meet plan criteria.
Most private and public plans offer some mental health benefits because of federal and state regulations, but the scope and mechanics differ by plan type and insurer. Coverage commonly depends on:
- Whether the therapist is in-network or out-of-network.
- Whether sessions are medically necessary and coded appropriately.
- Plan-specific limits (session caps, dollar caps, covered diagnoses).
- Preauthorization or referral requirements.
- Session modality (in-person vs. teletherapy).
According to a 2024 industry report, an increasing share of plans explicitly include outpatient mental health and substance use disorder services as essential benefits; however, coverage details still vary widely depending on employer, insurer, and state-level rules, so confirmation is required for each member and service.
Individual Therapy Program Overview and Psychological Counseling
Transition: Next, read how specific plan types commonly structure therapy benefits so you can compare your plan’s rules to industry norms.
Types of Insurance Plans and How They Cover Therapy
Answer: HMO, PPO, EPO, Medicaid, and Medicare each handle therapy differently—HMOs typically require in-network providers and referrals, PPOs offer more out-of-network flexibility, EPOs restrict out-of-network coverage, Medicaid and Medicare have program-specific rules and provider lists.
Term: Health insurance plans refer to specific product types (HMO, PPO, EPO, Medicaid, Medicare) that define how you access and pay for care.
Compare plan types at a glance in the table below, then read the practical details and typical limits for each.
| Plan type | Network rule | Common therapy coverage | Out-of-pocket notes |
|---|---|---|---|
| HMO | Must use in-network; PCP referrals often required | Outpatient therapy covered if in-network and authorized | Lower copays; limited out-of-network options |
| PPO | In-network preferred; out-of-network partial reimbursement | Broad coverage for psychotherapy; deductible may apply | Higher provider choice; higher cost if out-of-network |
| EPO | In-network only, no referrals but strict network | Covered in-network; no out-of-network benefits | Balance billing risk if you use out-of-network therapists |
| Medicaid | State-run program; provider lists vary by state | Often covers counseling and therapy; specialty limits apply | Low/no copay in many states; provider availability varies |
| Medicare | Part B covers outpatient therapy by eligible providers | Covers psychotherapy when provided by Medicare-authorized practitioners | Coinsurance and deductible may apply; supplemental plans help |
HMO details: HMOs generally require a primary care referral before behavioral health visits; check your plan’s referral and preauthorization rules. PPO details: PPOs reimburse out-of-network care at a lower rate—expect higher coinsurance and a need to submit claims if you see an out-of-network therapist. EPO details: EPOs commonly have no out-of-network benefits, so an in-network therapist is required for paid coverage.
Medicaid and Medicare specifics: Medicaid is state-administered and often covers community mental health services and counseling; rules and provider rosters vary by state. Medicare Part B covers outpatient psychotherapy delivered by qualified providers when services meet coverage criteria; Medicare Advantage plans may add more benefits.
Legal and policy context: Federal rules and state parity laws affect whether therapy is treated comparably to other medical benefits. For program details, consult authoritative sources such as the Centers for Medicare & Medicaid Services.
External resources: Centers for Medicare & Medicaid Services (CMS) — useful for Medicare/Medicaid specifics and program updates.
Transition: Now that you understand plan-level differences, learn which therapy types insurers commonly cover and how modality affects coverage.
What Kinds of Therapy Are Typically Covered by Insurance?
Answer: Insurers commonly cover evidence-based therapies (individual psychotherapy, CBT, group therapy, family therapy, behavioral therapy) when provided by credentialed clinicians and coded as medically necessary; coverage of specialized treatments varies.
Term: Counseling insurance benefits are the specific therapy services and session types a plan agrees to pay for under its policy rules.
Typical covered therapies:
- Individual psychotherapy (long- or short-term) — commonly covered when documented as medically necessary.
- Cognitive Behavioral Therapy (CBT) — frequently covered because of strong evidence base.
- Behavioral therapy for children (e.g., parent training, some autism services) — coverage varies by diagnosis and state rules.
- Group therapy and family therapy — often covered when part of treatment.
- Teletherapy (video/phone) — increasingly covered, though rules on platforms and geographic limits may apply.
Examples: A plan may cover 20 sessions per year of outpatient psychotherapy for major depressive disorder if documentation supports medical necessity; another plan may require preauthorization after 10 sessions. For behavioral therapy techniques and insurance relevance, see behavioral therapy techniques.
Coverage limits often hinge on:
- Diagnosis and documented medical necessity (insurers expect clinical notes and assessment codes).
- Provider credentials — some plans reimburse only licensed psychologists, clinical social workers, or psychiatrists.
- Session type — intake, individual, family, or group therapy may be coded differently.
For additional context on therapy types and how benefit design intersects with treatment options, see benefits of therapy types and treatments and best therapeutic approaches and effective therapy options.
Transition: Ready to confirm your own benefits? The next section gives a step-by-step verification process you can follow right now.
How to Check if Your Insurance Covers Therapy
Answer: Verify coverage by checking your insurance portal benefits, calling member services with specific questions, confirming therapist network status, asking about copays/deductibles/preauthorization, and documenting the answers.
Term: Verification process for insurance coverage is the set of steps you follow to confirm whether a plan covers a specific service for a specific provider.
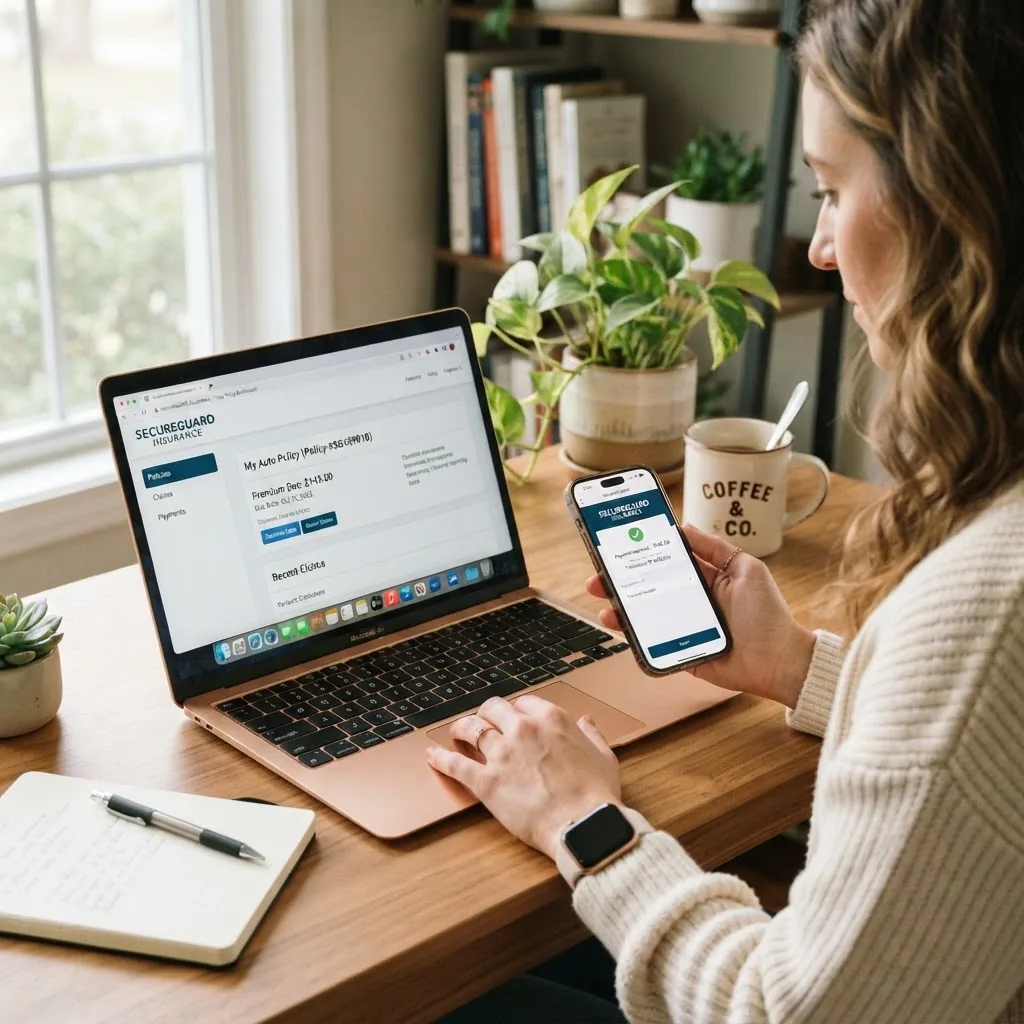
- Step 1 — Gather IDs and plan information.
Have your member ID, group number, employer plan name (if applicable), and therapist’s full name, license type, and NPI (National Provider Identifier) ready.
- Step 2 — Use the insurer’s online portal to view benefits.
Log in to your insurer’s member portal and look for “mental health,” “behavioral health,” or “outpatient services.” Note copay, coinsurance, deductible, session limits, and whether telehealth is allowed.
- Step 3 — Search the provider directory for in-network status.
Use the portal’s provider search or verify the therapist’s NPI to confirm in-network status; if the directory is unclear, proceed to Step 4 for confirmation.
- Step 4 — Call member services for precise answers.
Ask these exact questions and record the agent’s name, date, and reference number:
- “Is [therapist name] in-network for behavioral health?”
- “Are individual therapy sessions covered, and what is the copay/coinsurance and deductible?”
- “Is preauthorization required for initial or ongoing therapy?”
- “Are teletherapy sessions eligible for the same benefit?”
- “Are there session or dollar limits per year?”
- Step 5 — Confirm billing codes and diagnosis rules.
Ask which CPT (Current Procedural Terminology) codes and diagnosis codes the plan accepts for psychotherapy so the provider can bill correctly; common codes begin with 9083x for psychotherapy.
- Step 6 — Verify claims and reimbursement process.
Ask whether the provider files claims on your behalf (in-network typically does) and how out-of-network reimbursement works; request timelines for claim processing and appeals.
- Step 7 — Document everything.
Save screenshots, agent notes, reference numbers, and any written confirmations via secure messages or email to the insurer and provider for future disputes.
- Step 8 — If needed, get preauthorization in writing.
When preauthorization is required, secure written approval or a reference number and follow the insurer’s appeals process if authorization is denied.
- Step 9 — Find covered providers if needed.
If your therapist is out-of-network or not covered, use insurer directories, the provider’s office to confirm which plans they accept, or find a CBT therapist near me to locate alternatives.
Walkthrough example: On a typical insurer portal you’ll navigate to “Benefits,” choose “Behavioral Health,” then see a summary of copays and limits; if details are missing, call member services and quote the exact plan code. Document the agent’s confirmation for your records.
Case study: Sarah called member services, asked whether her licensed clinical social worker was in-network, and had the agent confirm an $25 copay and no preauthorization for the first 12 sessions; she saved the reference number and had the provider verify billing codes ahead of the first session.
External verification resources: For private plan marketplace questions, consult Healthcare.gov for marketplace plan structures and benefit explanations.
Transition: With verification complete, you’ll better understand terms that determine cost—read the next section for plain-language definitions of those terms.
Common Insurance Terms Related to Therapy Coverage Explained
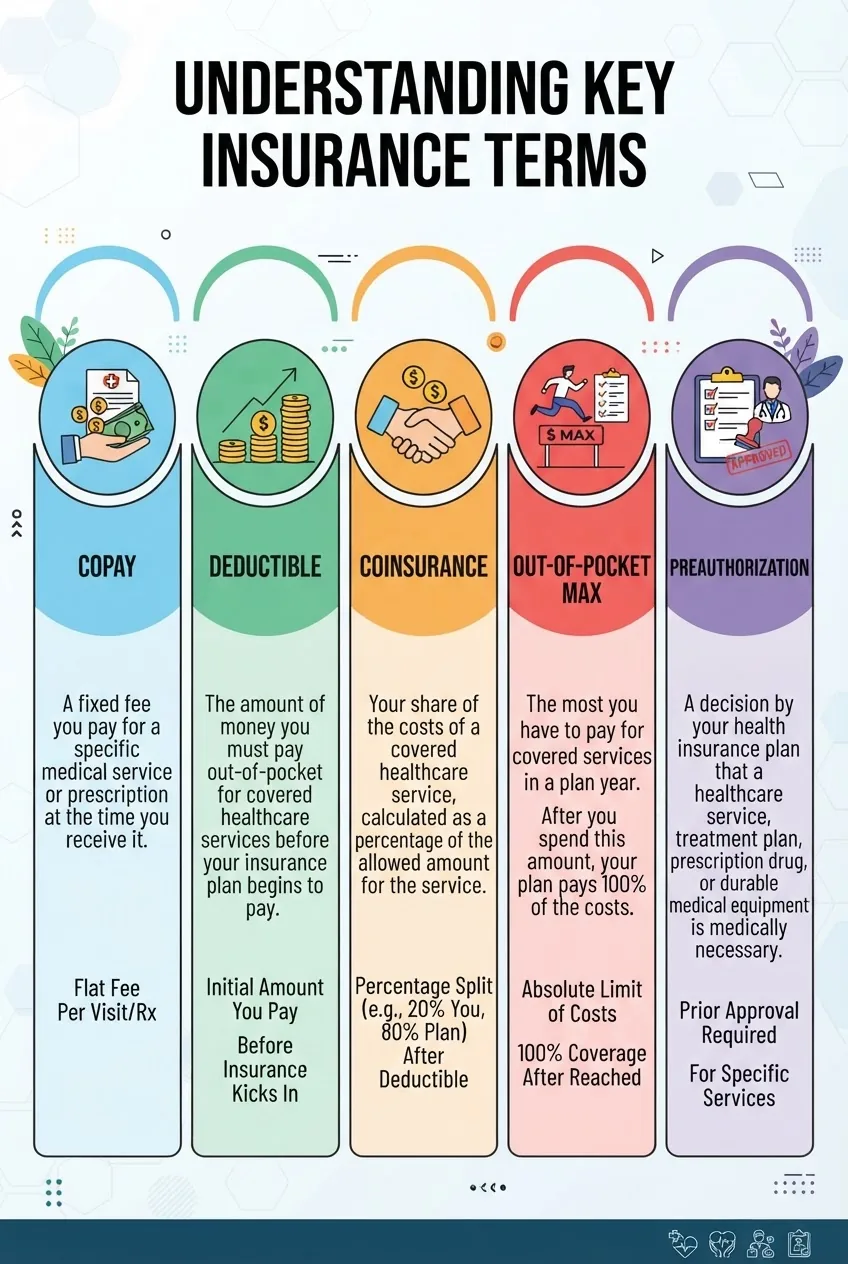
Answer: Key terms—copayment, coinsurance, deductible, out-of-pocket maximum, preauthorization, and referral—define your financial responsibility and administrative steps insurers require for therapy coverage.
- Copayment (copay):
Term: A fixed amount you pay at each visit (for example, $25 per therapy session). Example: If your copay is $25, you pay $25 and the insurer covers the remainder according to plan rules.
- Deductible:
Term: The amount you pay out-of-pocket before insurance begins to contribute. Example: If your deductible is $1,000, you usually pay full costs until spending reaches $1,000, after which coinsurance applies.
- Coinsurance:
Term: A percentage of costs you pay after meeting the deductible (for example, 20%). Example: With 20% coinsurance, you pay $20 of a $100 session after deductible is met.
- Out-of-pocket maximum:
Term: The yearly cap on what you pay in deductibles, copays, and coinsurance; after reaching it, the plan covers 100% of covered services. Example: A $5,000 maximum limits your total cost exposure for the plan year.
- Preauthorization (prior authorization):
Term: Formal approval from the insurer before certain services to confirm they will be covered. Example: The insurer may require preauthorization for more than 20 sessions per year.
- Referral requirement:
Term: When a primary care provider must authorize specialty visits for coverage (common in HMOs). Example: Without a referral, therapy visits might be denied as out-of-network.
- In-network vs. out-of-network:
Term: In-network providers have contract rates with the insurer; out-of-network do not. Example: In-network sessions typically cost less, and out-of-network may require you to submit claims or face balance billing.
Scenario illustrating differences: If a PPO member has a $1,500 deductible, 20% coinsurance, and a $30 copay for in-network therapy, their cost for a $150 session before meeting deductible might be $150; after meeting deductible, they might pay 20% ($30) plus any remaining copay rules. If the therapist is out-of-network, they may pay more and need to file a claim.
Transition: Understanding terms helps you compare actual costs; next, see cost examples with and without insurance, including sliding-scale and teletherapy options.
Costs of Therapy Sessions With and Without Insurance
Answer: Insurance can reduce per-session cost via copays or reimbursements, but actual out-of-pocket depends on network status, deductibles, coinsurance, and session limits; uninsured self-pay rates and sliding-scale options provide alternative pricing.
Term: Out-of-pocket costs are the money you personally pay for therapy, including copays, deductible payments, coinsurance, and services not covered by insurance.
Average pricing context: According to a 2024 industry report, average private-pay therapy session rates in the U.S. range from $100–$250 per session depending on region and provider credentials; insurance copays often fall between $10–$50 for in-network sessions.
Examples comparing in-network vs out-of-network costs:
- Example A — In-network (PPO) with $30 copay: You pay $30 per session; insurer covers the negotiated rate remainder.
- Example B — High-deductible plan: You pay full session cost ($120) until you meet the deductible, then coinsurance applies (e.g., 20% of $120 = $24).
- Example C — Out-of-network: Provider charges $150; insurer reimburses 60% of “usual, customary, and reasonable” (UCR) rate ($90), leaving you responsible for $60 plus any difference between provider charge and UCR rate.
Sliding scale and affordability: Many therapists offer sliding scale therapy based on income; see sliding scale counseling near me for options. Employee Assistance Programs (EAPs) may provide several free therapy sessions through your employer.
Statistics and authority: According to a 2023 CMS report, Medicare beneficiaries commonly face coinsurance and deductibles for outpatient mental health, while Medicaid enrollees often have low or no copays depending on state rules.
Cost-lowering strategies:
- Choose in-network therapists to reduce copays and eliminate balance billing.
- Ask providers about sliding scale options or reduced-frequency plans (e.g., twice-monthly sessions).
- Use EAP benefits for short-term counseling where available.
- Compare private-pay rates and request a superbill (itemized receipt) for out-of-network reimbursement.
For more on therapy benefits tied to costs, see benefits of individual therapy and counseling sessions and for detailed session pricing research, see how much are therapist sessions.
Transition: If insurance won’t cover your therapy or you need lower-cost options, the next section lists practical alternatives and resources.
Alternatives When Insurance Does Not Cover Therapy
Answer: If insurance doesn’t cover therapy, consider sliding-scale therapists, community mental health centers, EAP counseling, cash-based clinicians, online low-cost platforms, or evidence-based self-help tools and worksheets.
Term: Sliding scale therapy is a payment model where the therapist adjusts fees based on income or ability to pay.
Options and resources:
- Sliding scale clinics and private therapists — search sliding scale counseling near me for local options.
- Community mental health centers — often offer low-cost or income-based services and can bill Medicaid where applicable.
- Employee Assistance Programs (EAP) — free short-term counseling for employees and dependents; contact HR to access.
- University training clinics — supervised trainees offer lower-cost therapy under licensed oversight.
- Teletherapy platforms and subscription-based mental health apps — can reduce per-session price.
- Self-help and guided CBT resources — when coverage is unavailable, use CBT therapy exercises and worksheets to supplement care.
- Local counseling centers — see counseling centers near me.
Real-world example: Mark was denied out-of-network coverage, so he switched to a graduate clinic charging $45 per session and used online guided CBT workbooks between appointments to maintain progress.
Transition: Whether insured or self-paying, you can often increase coverage or reduce costs—read practical tips next.
Tips for Maximizing Your Insurance Benefits for Therapy
Answer: To maximize benefits, select in-network therapists, verify and document benefits, obtain preauthorization when required, use EAPs, file accurate claims, and appeal denials with supporting clinical documentation.
Term: Preauthorization (see earlier) is insurer approval prior to service; failing to secure it may lead to denial.
- Choose in-network providers when possible.
In-network therapists have negotiated rates and simpler claims processes, reducing your out-of-pocket exposure.
- Confirm billing codes and diagnosis requirements.
Ask the therapist which CPT codes they use and ensure they match the insurer’s accepted codes for therapy services to avoid claims rejections.
- Get preauthorization and referrals in writing.
Request written approvals and save confirmation numbers; use these if a claim is denied and you need to appeal.
- Use EAP benefits first for short-term counseling.
Many employers provide EAP sessions that don’t count against plan limits; use them as an initial resource.
- File accurate claims and track payment.
Confirm the provider submits claims with correct codes; if out-of-network, request a superbill so you can submit claims yourself.
- Appeal denials promptly and with documentation.
If a claim is denied, request the denial reason, submit progress notes and clinical justification, and follow the insurer’s appeal timeline carefully.
- Negotiate or request reduced rates where appropriate.
Some providers will offer a sliding-scale retroactively or a cash-pay discount; discuss options before scheduling.
- Document all communications.
Keep written records, reference numbers, and names for every insurer conversation; this improves success in disputes and appeals.
Expert tip: When filing an appeal, cite the Mental Health Parity and Addiction Equity Act if you believe mental health benefits are treated less favorably than medical benefits—this legal framework supports equitable coverage. For advocacy and parity information, see National Alliance on Mental Illness (NAMI).
Transition: The final section summarizes next steps and a short checklist to prepare for your first covered session.
Summary and Next Steps for Accessing Covered Therapy Services
Answer: Verify your plan’s benefits, confirm therapist network status and billing codes, document insurer confirmations, get preauthorization if required, and choose cost-saving options when needed.
- Check your plan’s behavioral health benefits in the member portal and call member services for specifics.
- how counseling therapy works — review therapy formats and what to expect.
- Confirm therapist in-network status and accepted CPT codes; secure preauthorization when required.
- Prepare to provide diagnosis and clinical notes if appealing a denial; document all insurer communications for disputes.
- Explore EAPs, sliding scale options, community clinics, or self-help resources if coverage is limited.
Next step (CTA): Use the verification steps above now—log into your insurer portal, call member services with the script provided, and schedule an initial intake with a therapist who accepts your plan or offers an accessible sliding scale.